How to Registration Company Shares: Common vs. Preferred Stock Explained
Learn how to registration company shares in India, compare common and preferred stock, understand investor rights, and plan equity distribution wisely.
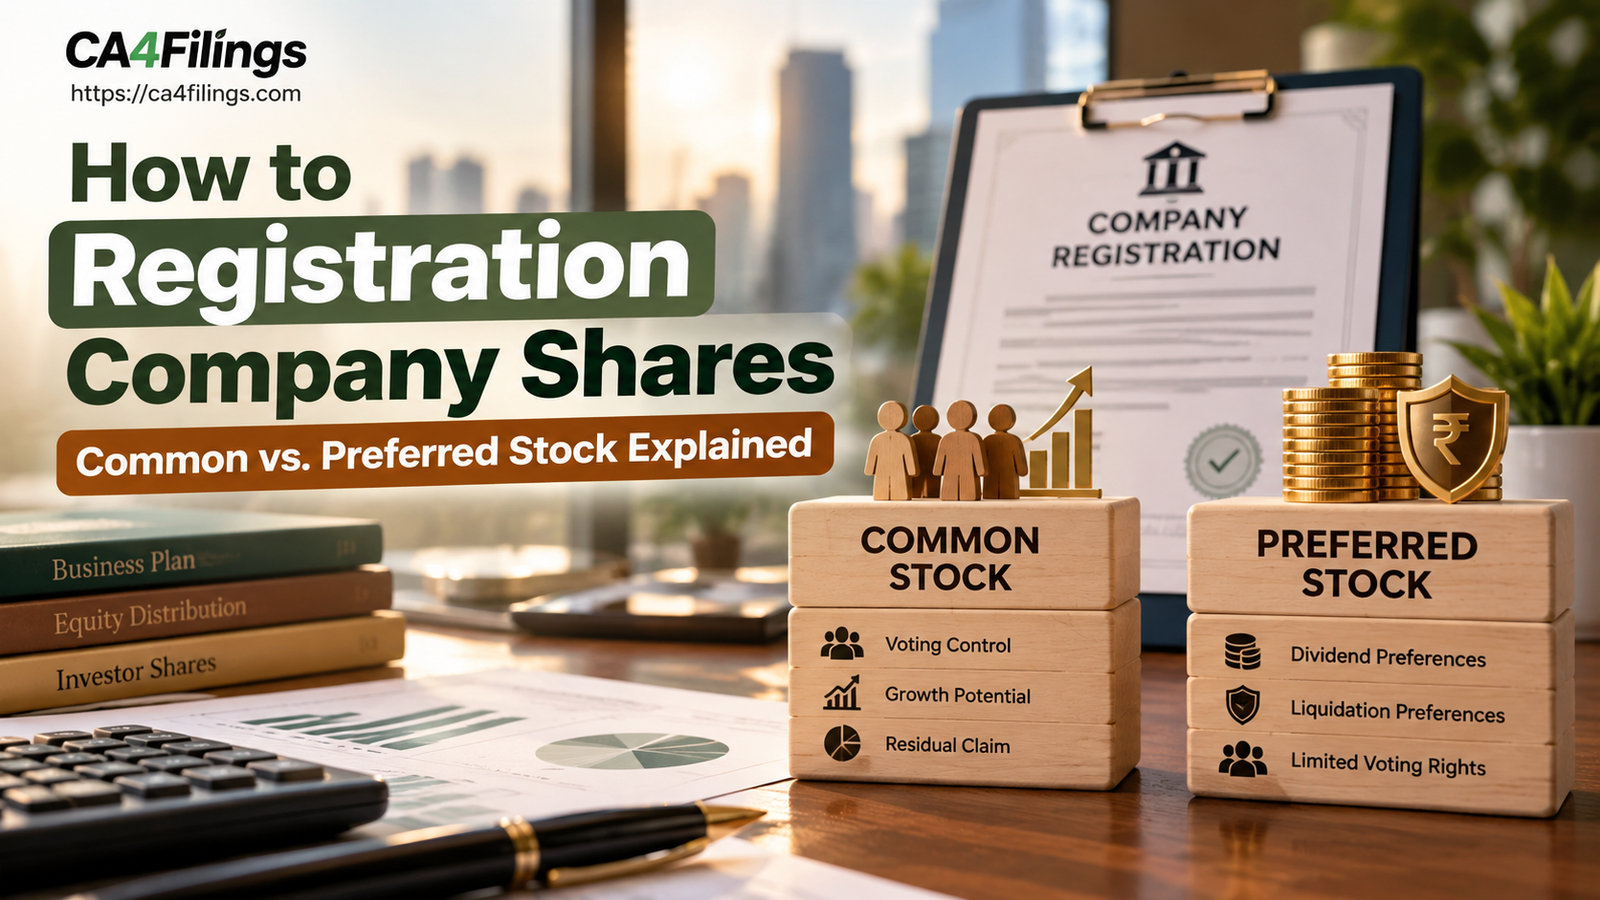
Understanding Company Share Registration in India
Starting a business involves more than choosing a name and completing legal formalities. One of the most important decisions is determining how ownership will be divided among founders, investors, and other shareholders. If you are researching how to registration company shares, understanding the difference between common and preferred stock is an essential first step.
In India, companies generally issue equity shares and preference shares under the Companies Act, 2013. Each type comes with different rights relating to voting, dividends, and repayment of capital during liquidation. Choosing the right structure can help protect founder stock, attract investors, and maintain effective voting control as your business grows.
At CA4Filings, we guide entrepreneurs through incorporation, share capital planning, and statutory compliance. Our Company Registration services help business owners establish the right legal foundation before issuing shares or bringing investors on board.
How to Registration Company Shares: The Basics
Before issuing shares, you must understand your company's legal structure and the rights attached to each share class.
In India, a private limited company and a public limited company can issue shares in accordance with the Companies Act, 2013, their constitutional documents, and applicable regulations.
The process generally involves:
Deciding the company's authorised and paid-up share capital.
Determining the number and face value of shares.
Identifying the initial shareholders and their ownership percentages.
Defining the rights attached to each class of shares.
Issuing shares and maintaining the required statutory records.
For example, suppose two founders establish a private limited company with an initial paid-up capital of ₹1,00,000, divided into 10,000 equity shares of ₹10 each. If each founder receives 5,000 shares, both initially own 50% of the company.
However, if the company later raises funds from an investor, the equity distribution may change. The founders must therefore consider both immediate ownership and future fundraising requirements.
Common Shares vs Preferred Stock: What Is the Difference?
Understanding the distinction between common and preferred stock helps business owners make informed decisions about investor shares and ownership rights.
In Indian company law, these terms broadly correspond to equity shares and preference shares, although the precise rights depend on the company's legal documents and applicable law.
1. Common Shares (Equity Shares)
Equity shares represent ordinary ownership in a company. Shareholders generally participate in the company's growth and may receive dividends when declared by the company.
Key features include:
Voting rights: Equity shareholders ordinarily have voting rights, subject to applicable law and the terms of the share class.
Capital appreciation: Their investment may increase in value as the business grows.
Dividend entitlement: Dividends are not guaranteed and depend on profits, legal requirements, and the necessary corporate approvals.
Residual claim: In liquidation, equity shareholders receive any remaining assets only after liabilities and prior-ranking claims have been settled.
Example: A founder owns 6,000 out of 10,000 equity shares. The founder holds 60% of the equity share capital. If the company becomes more valuable, the founder may benefit from that growth, although the actual return depends on business performance and future dilution.
For most founders, equity shares are the primary means of establishing founder stock and determining initial voting control.
2. Preferred Stock (Preference Shares)
In India, preference shares provide preferential rights concerning dividends and repayment of capital, subject to their terms and applicable law.
They are often used when companies want to raise capital while offering investors specific financial protections.
Their common features include:
Dividend preferences: Preference shareholders generally receive priority over equity shareholders for dividends, in accordance with the applicable terms.
Liquidation preferences: They receive priority over equity shareholders for repayment of capital on winding up, subject to statutory requirements and the relevant class rights.
Defined financial terms: Shares may carry cumulative or non-cumulative dividends and participating or non-participating rights.
Restricted voting rights: Voting rights are governed by the Companies Act, 2013, and the terms of issue. Preference shareholders do not necessarily enjoy the same voting rights as ordinary equity shareholders.
Example: A startup raises ₹50 lakh by issuing preference shares to an investor. The terms may provide a specified preferential dividend and priority repayment of capital during winding up. The investor gains defined protections, while the founders may preserve more ordinary equity voting power.
Preference shares are not automatically the same as the convertible preferred shares commonly used in overseas venture capital transactions. Indian companies must structure any conversion rights in accordance with applicable law and their issue terms.
How to Registration Company Shares: Step-by-Step Process
Once you understand the available share classes, the next step is to organise the issuance properly.
Step 1: Choose the Right Company Structure
Decide whether a private limited company or another suitable business structure meets your requirements. Your choice affects ownership, fundraising opportunities, compliance obligations, and the manner in which shares can be issued.
Step 2: Determine Authorised and Paid-Up Capital
Authorised capital represents the maximum share capital the company is authorised to issue under its constitutional documents, subject to applicable requirements. Paid-up capital represents the amount credited as paid on issued shares.
For example, a company may have authorised capital of ₹10 lakh but initially issue shares worth ₹1 lakh. The remaining authorised capacity may support future share issues, subject to the necessary approvals and procedures.
Step 3: Decide the Share Classes and Rights
Determine whether the company needs equity shares, preference shares, or multiple classes of shares.
Consider the following questions:
Who needs voting control?
Will investors receive dividend preferences?
Should investors have liquidation preferences?
Will future fundraising dilute the founders' ownership?
Are any special rights required to be documented in the articles of association and issue terms?
Obtain professional advice before finalising these arrangements.
Step 4: Complete the Necessary Approvals
Depending on the transaction, the company may need board approval, shareholder approval, amendments to its articles, valuation documentation, and compliance with private placement or preferential allotment rules.
The precise requirements depend on the type of issue, the company's existing documents, and the applicable provisions of the Companies Act, 2013.
Step 5: Issue Shares and Update Records
Complete the applicable allotment and filing formalities. These may include filing Form PAS-3 with the Registrar of Companies, issuing share certificates where required, maintaining the register of members, and complying with applicable stamp duty requirements.
Shares issued in dematerialised form are subject to the relevant depository and securities requirements.
CA4Filings tip: Do not treat share issuance as a simple paperwork exercise. Incorrect approvals, incomplete records, or improperly documented investor rights can create avoidable legal and financial complications later.
How Equity Distribution Affects Founders and Investors
A well-planned equity distribution balances founder ownership with the company's need for external capital.
Consider a startup with the following initial ownership:
Founder A: 50%
Founder B: 30%
Founder C: 20%
If the company subsequently issues new shares to an investor, the founders' ownership percentages may decrease. This is known as dilution.
Before accepting funding, founders should review:
The percentage ownership they will retain after investment.
Whether the investor receives ordinary equity or preference shares.
The impact of voting rights on management decisions.
Any dividend preferences or liquidation preferences.
Future fundraising plans and employee stock option requirements.
An investor offering a higher valuation may not necessarily be the best choice if the proposed terms significantly affect founder control or impose unfavourable financial preferences.
The right decision depends on the company's funding needs, growth plans, and the complete terms of the investment.
Common Mistakes to Avoid When Registering Company Shares
Business owners should avoid these frequent mistakes:
Issuing shares without obtaining the required approvals.
Ignoring restrictions in the articles of association.
Assuming that preference shareholders never have voting rights.
Promising dividends without considering legal requirements and distributable profits.
Overlooking dilution when negotiating with investors.
Failing to maintain accurate statutory registers and allotment records.
Using informal agreements without properly documenting shareholder rights.
Professional guidance at the beginning can prevent expensive restructuring and shareholder disputes later.
Latest Updates
ca4filings.com Services